
As we bid farewell to another TFWA (Tax Free World Association) World Exhibition & Conference in Cannes, I have been reflecting on some discussions with industry peers at the event this year.
Firstly, the future of the GTR channel remains bright….even if the growth is not to the level of your budget projections this year! Clearly some companies have been bullish with their internal targets for the channel, however international travel will continue to increase globally, as reported by ForwardKeys, and we have moved beyond the initial post-pandemic recovery phase. The channel remains an important market for brands and this will continue going forward, both commercially and in marketing terms.
 Secondly, we need to constantly remind ourselves that the shop floor staff in the GTR channel are also, in most cases, the first friendly faces that travellers see when entering a new country and when leaving to return home. Investment in their development and training is critical. We are after all in the entertainment retail business and the harsh reality is that people don’t really need our products. Our biggest categories are flavoured water and fragrant water. We need to excite our travellers to convert them into shoppers and avoid the obvious pitfalls, such as the Shopping Mall Syndrome (where all stores look the same and have the same brands) to allow for store penetration levels to grow again.
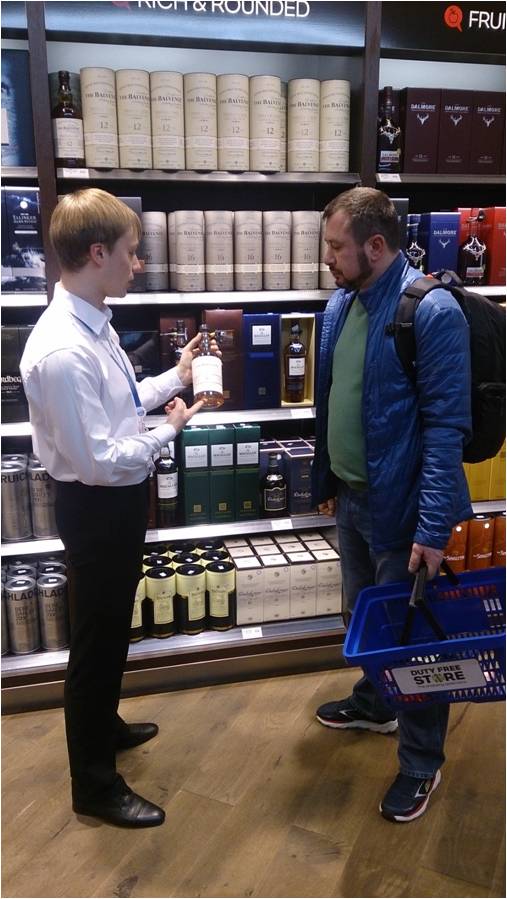
Think about it. If we continue to offer the same staff training, with the same store brand displays, offering the same range of products, and with the same bottle formats, there will be no change in the behaviour of consumers as we have offered little to no variety, instead prioritising to be as efficient as possible. As the famous quote suggests “insanity is doing the same thing over and over again and expecting different results”.
It is crucial that we embrace innovation trends from domestic markets, trial different approaches and bottle formats and support new entrants into the GTR channel.

Perhaps bridging the potential disconnect between leadership teams and shop floor staff at GTR operators could be one such way for this need for change to be recognised more quickly. It would certainly help to provide a better understanding of the barriers to purchase on the shop floor impacting on the sales fundamentals.
There is also a continued need for engagement to drive conversion not just within stores, but also beyond its walls during their dwell time….where are the blended retail concepts in GTR (such as F&B and Retail combined within the same area)? I can understand the challenges of bringing this to life due to the tender process in GTR for operators to secure F&B or Retail licenses, but this is where the landlords, such as Airports, could be driving the agenda and influencing the operators to develop new formats.
 Thirdly, data, or the lack of access to it, continues to be a hot topic of discussion within the GTR channel. Data is critical to generate consumer insights and improve the delivery of the sales fundamentals to influence consumer behaviour but unfortunately, we are still not on full collaboration mode in the GTR channel….so suppliers must seek out data where it is available (e.g. IWSR, TR Pricewatch, etc). This is a completely different position to Domestic markets where brands have access to significant amounts of data and can work in partnership with operators to develop the overall category growth, especially as resource is inevitably limited to analyse data when working unilaterally.
On a final point of reflection, we need to protect the GTR channel and be careful not to erode one of its key pillars to consumers – its value proposition vs. domestic markets!


0 Comments